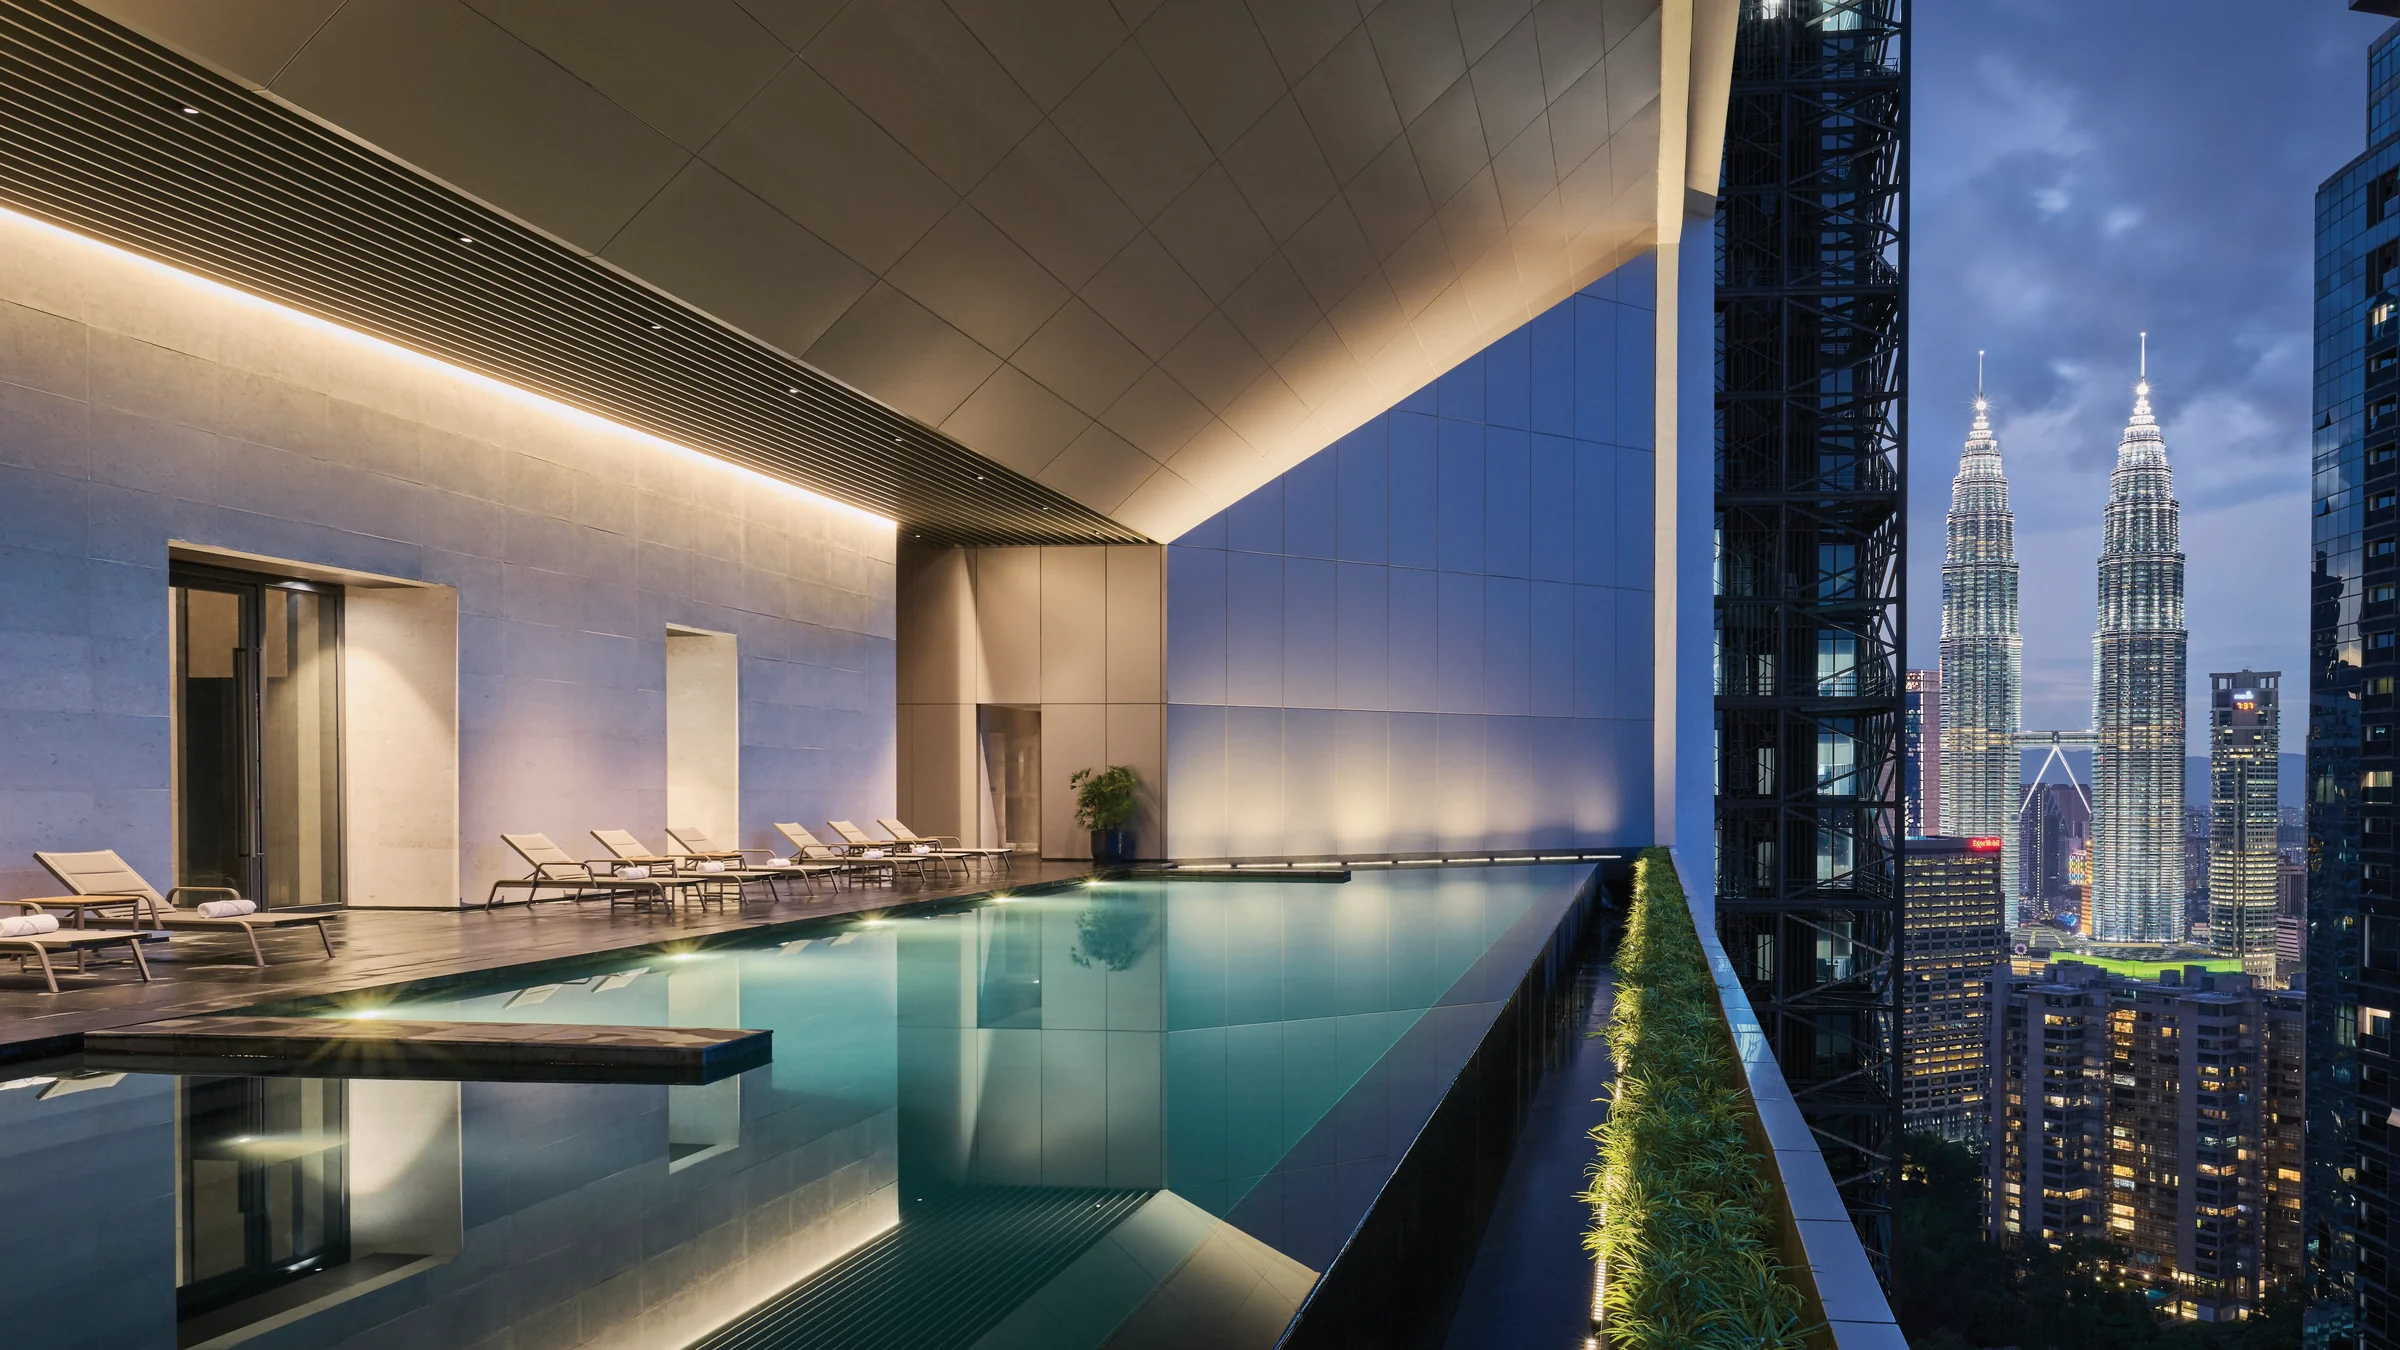
Yes. Malaysian banks lend to Malaysians working overseas on a foreign salary, up to 90% of the price, the same limit as at home. Each bank decides case by case, from your credit record, your job and your other loans. With a 90% loan at The Atera, from RM691,400, the monthly instalment is about RM2,755, which a net salary of about S$1,600 a month covers.
- Up to 90% loan: the most allowed on your first and second home loans. A clean credit record and a steady job help you to the top of it, while a foreigner is usually offered 50% to 60%.
- Your foreign salary counts: banks convert it to ringgit and usually count 70% to 90% of it, and at S$1 to about RM3.17 a Singapore salary goes a long way.
- The Malaysian price list: you pay the Malaysian stamp duty scale, not the 8% for foreigners, and you can buy homes below RM1mil and projects foreigners cannot buy at all.
- Buy from where you live: many developers and banks let you sign abroad, before a notary or at a Malaysian embassy, and we tell you which ones before you book.
Not sure where you stand? WhatsApp us and we look at your case, as every bank and every buyer is different.
Why buy a home in Malaysia while you earn overseas?
- Your salary buys more at home: at S$1 to RM3.17, The Atera, from RM691,400, is about S$218k.
- A home that pays its way: rent it out while you are abroad, and the rent goes towards the instalment.
- A home for your family: a new home for your parents now, and for you when you come back.
- The earlier you buy, the longer the loan: loans run until age 70 at most, so every year you wait shortens the loan and raises the instalment.
How much salary do you need for a home loan in Malaysia?
Three new launches, if the bank lends 90% at 4% over 35 years, counts 80% of your salary and lets the loan take up to 70% of it. In Singapore dollars at S$1 to RM3.17 (July 2026).
| The Atera | OAKA Residences | Accent Residences | |
|---|---|---|---|
| From | RM691,400 | RM854,000 | RM1.15mil |
| 90% loan | RM622,260 | RM768,600 | RM1.035mil |
| Monthly instalment | RM2,755 | RM3,403 | RM4,583 |
| Net salary needed | S$1,600 (RM4,920) | S$1,900 (RM6,077) | S$2,600 (RM8,183) |
| Cash to sign | RM102,600 | RM127,600 | RM174,500 |
Free loan check for your salary
Send us your latest payslip on WhatsApp. Within the day we tell you:
- What the banks are likely to lend on your salary
- Which banks count the most of it
- The homes that fit, with the cash to sign
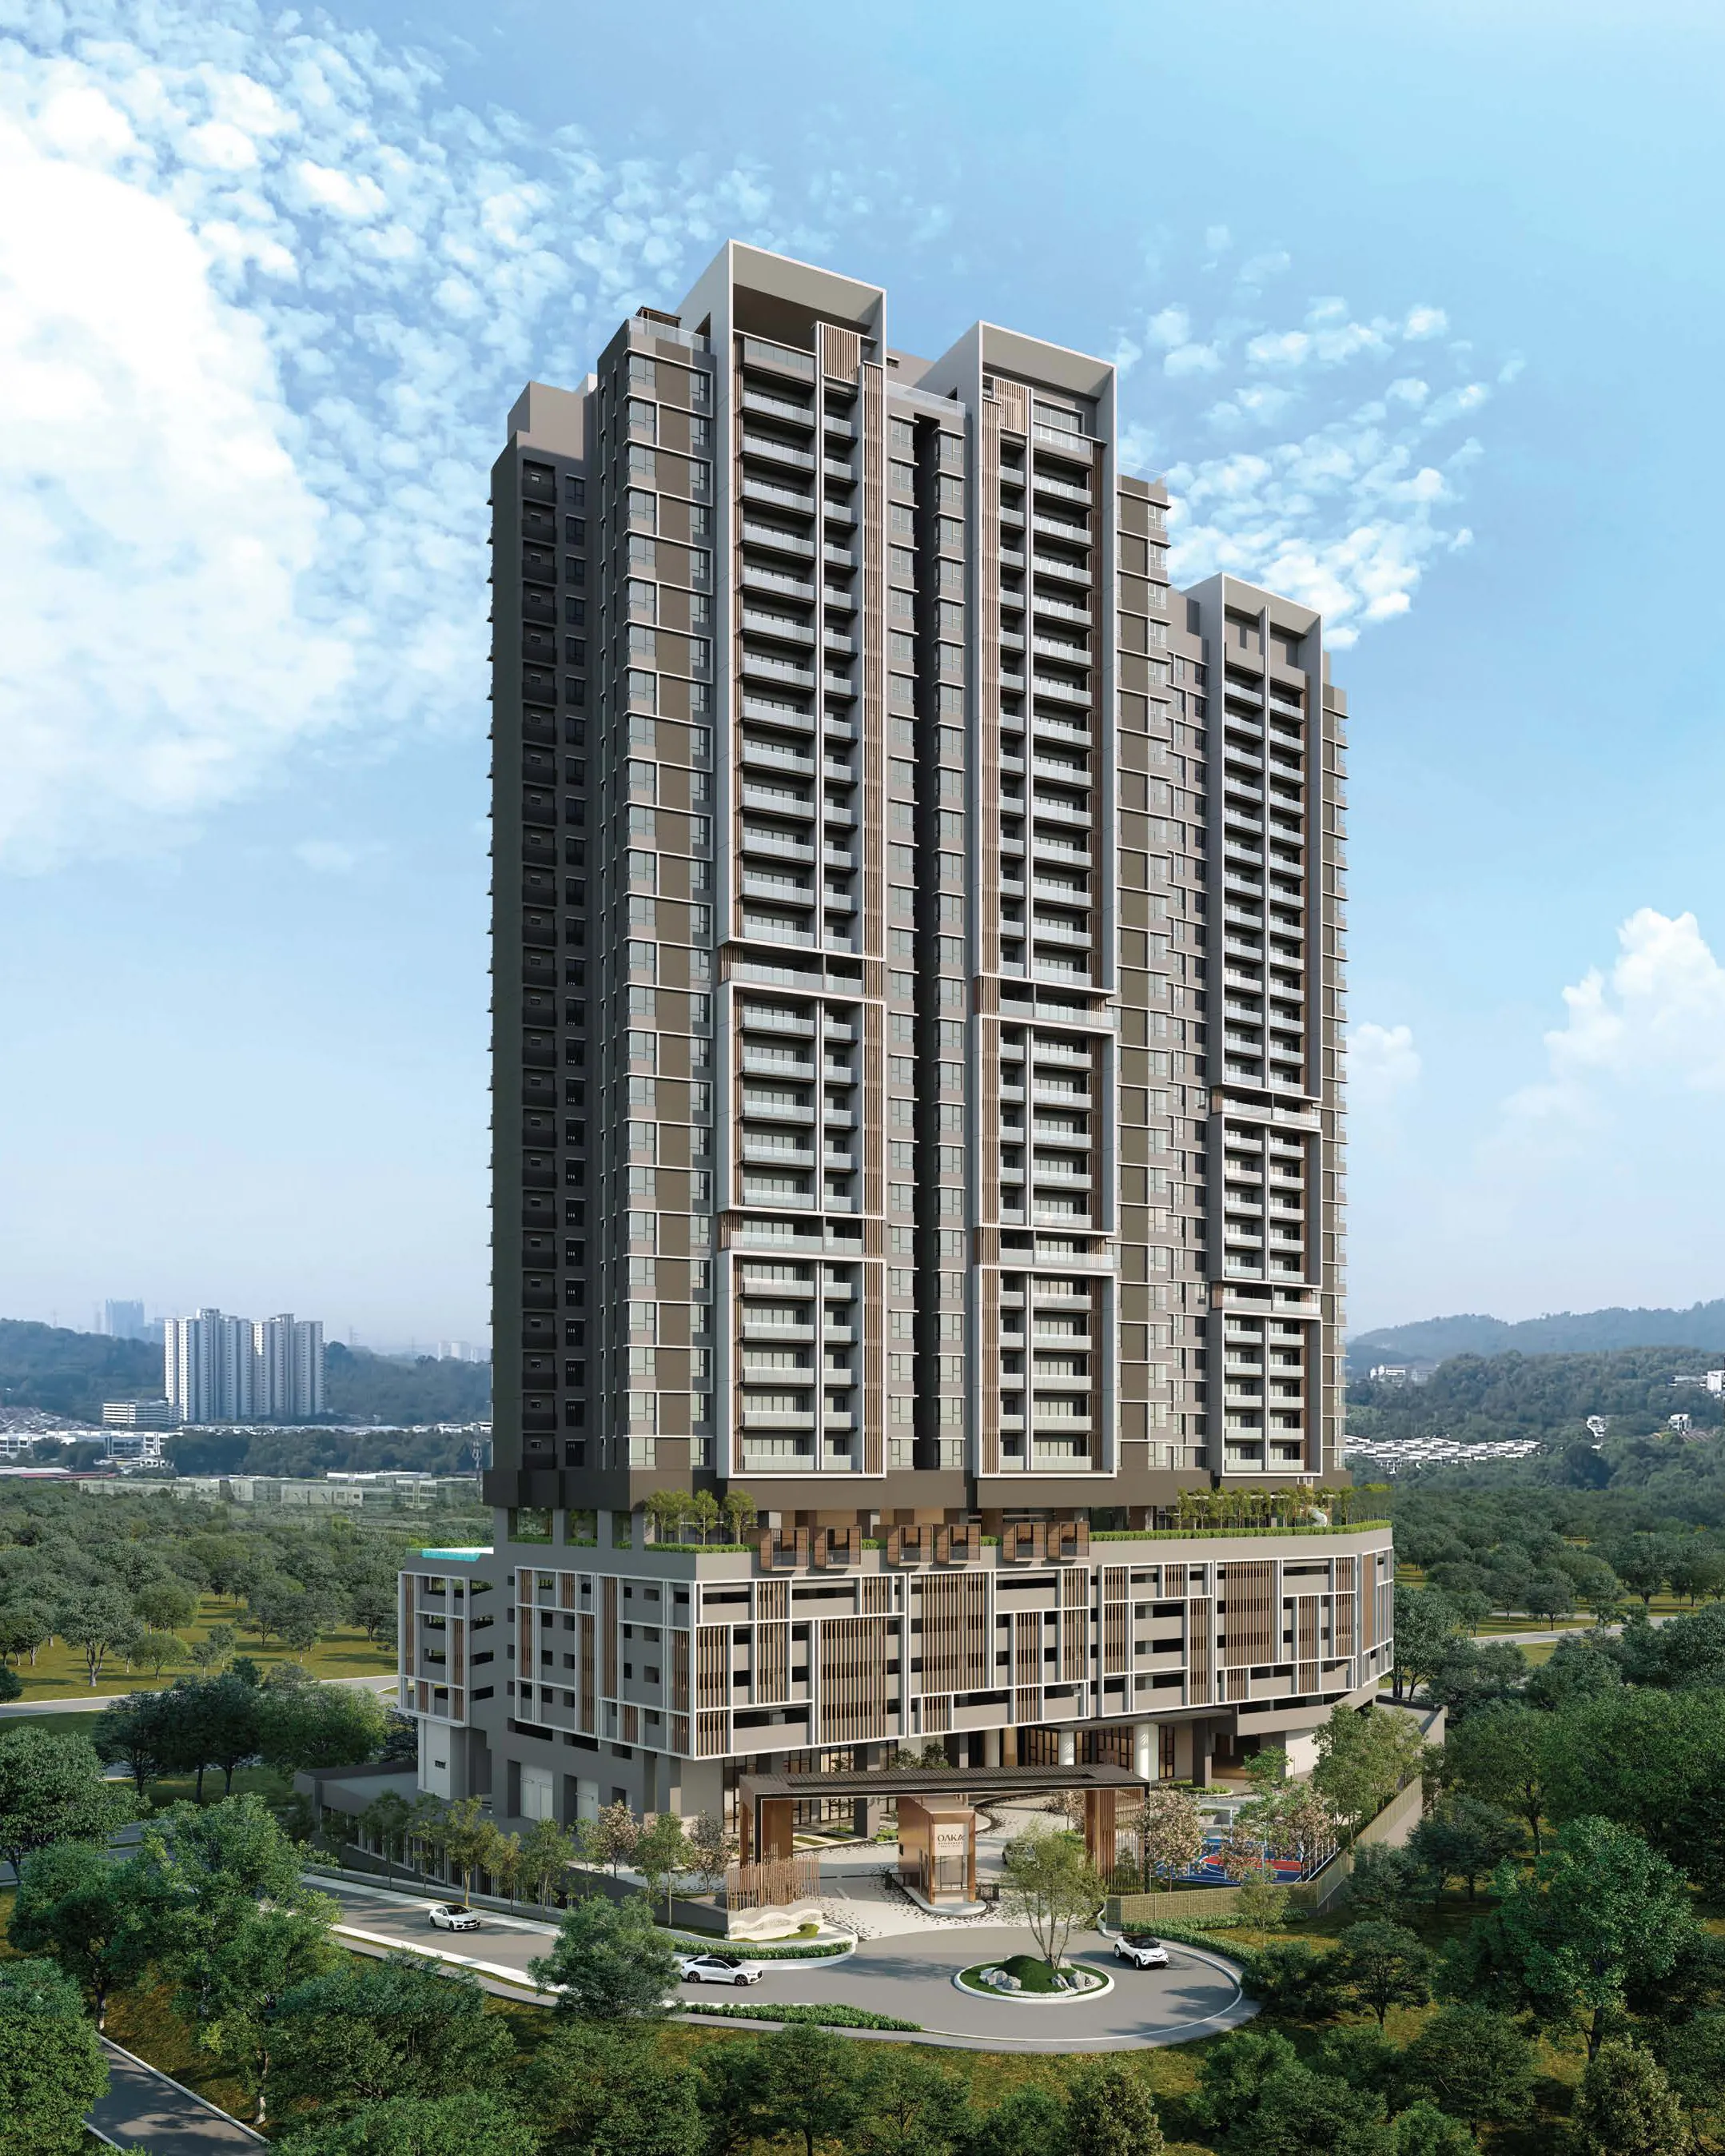
Artist’s impression · OAKA Residences, freehold beside the Bukit Jalil golf course
- What decides your loan: your credit record in Malaysia and where you work, your job and employer, how long you have been there, your other loans, and whether a co-borrower or guarantor joins. Even when you meet every criterion, the bank has the final say, so we go through your case with you before you apply and send it to the banks most likely to say yes.
- Other loans count too: a car loan or credit card balance abroad is added to your commitments, so work out your figure on our DSR calculator.
- Two salaries: a joint loan with your spouse adds both incomes, wherever each of you works. Many banks also accept a parent or sibling in Malaysia as co-borrower, each on its own terms.
- Your EPF: savings from your years working in Malaysia can go towards the down payment, from Account 2 (now called Akaun Sejahtera), on KWSP’s conditions at the time you apply.
- Loan length: usually up to 35 years or until age 70, whichever comes first, depending on the bank.
- Pay in stages: on a home being built the bank pays the developer as the tower goes up, and you pay interest only on what has been paid out, so the full instalment starts near keys.
- Monthly instalment: see the figure for your loan on our home loan calculator.
How much less cash does a Malaysian need than a foreigner?
The cash to sign, at the same three prices: the down payment, stamp duty and legal fees. A foreigner usually borrows 50–60%, pays 8% stamp duty and cannot buy below RM1mil in Kuala Lumpur or RM2mil in Selangor.
| The Atera | OAKA Residences | Accent Residences | |
|---|---|---|---|
| You, as a Malaysian | RM102,600 | RM127,600 | RM174,500 |
| A foreigner, at this price | Cannot buy | Cannot buy | Cannot buy |
A foreigner cannot buy any of these three at its starting price: The Atera and Accent Residences are for Malaysians only, and OAKA Residences starts below the foreign minimum. All three are open to you. See every project in our new launches list, all of them open to Malaysians.
- First home? Budget 2027 proposes no stamp duty on the first RM500,000 for Malaysian citizens buying a first home up to RM750,000, on SPAs from 1 January 2027 once passed. At The Atera that saves about RM14,700. See our Budget 2027 guide.
- When you sell: you pay real property gains tax as a Malaysian, 0% from year 6. See our RPGT guide.
What documents do banks need from Malaysians working overseas?
Most banks start with the list below, from your country of work. Each bank may ask for more, and what it asks for changes with your job and its own rules, so we tell you what your bank needs before you apply.
- Identity: your MyKad and passport.
- Your job: an employment letter or contract showing your position, salary and start date.
- Salary: payslips for the last 3 to 6 months, and bank statements showing the salary paid in.
- Tax: your latest tax assessment where you work, such as the IRAS Notice of Assessment in Singapore, plus your CPF statement if you are in Singapore.
- Credit: a credit report from the country where you work, such as Credit Bureau Singapore, if the bank asks.
- Self-employed: usually your tax assessments and business accounts for the last two years, in place of payslips.
- The home: the booking form or SPA, which we send you with the price list.
Contract job, business of your own, or an income that varies? WhatsApp us and we look at your case, as every bank and every buyer is different.
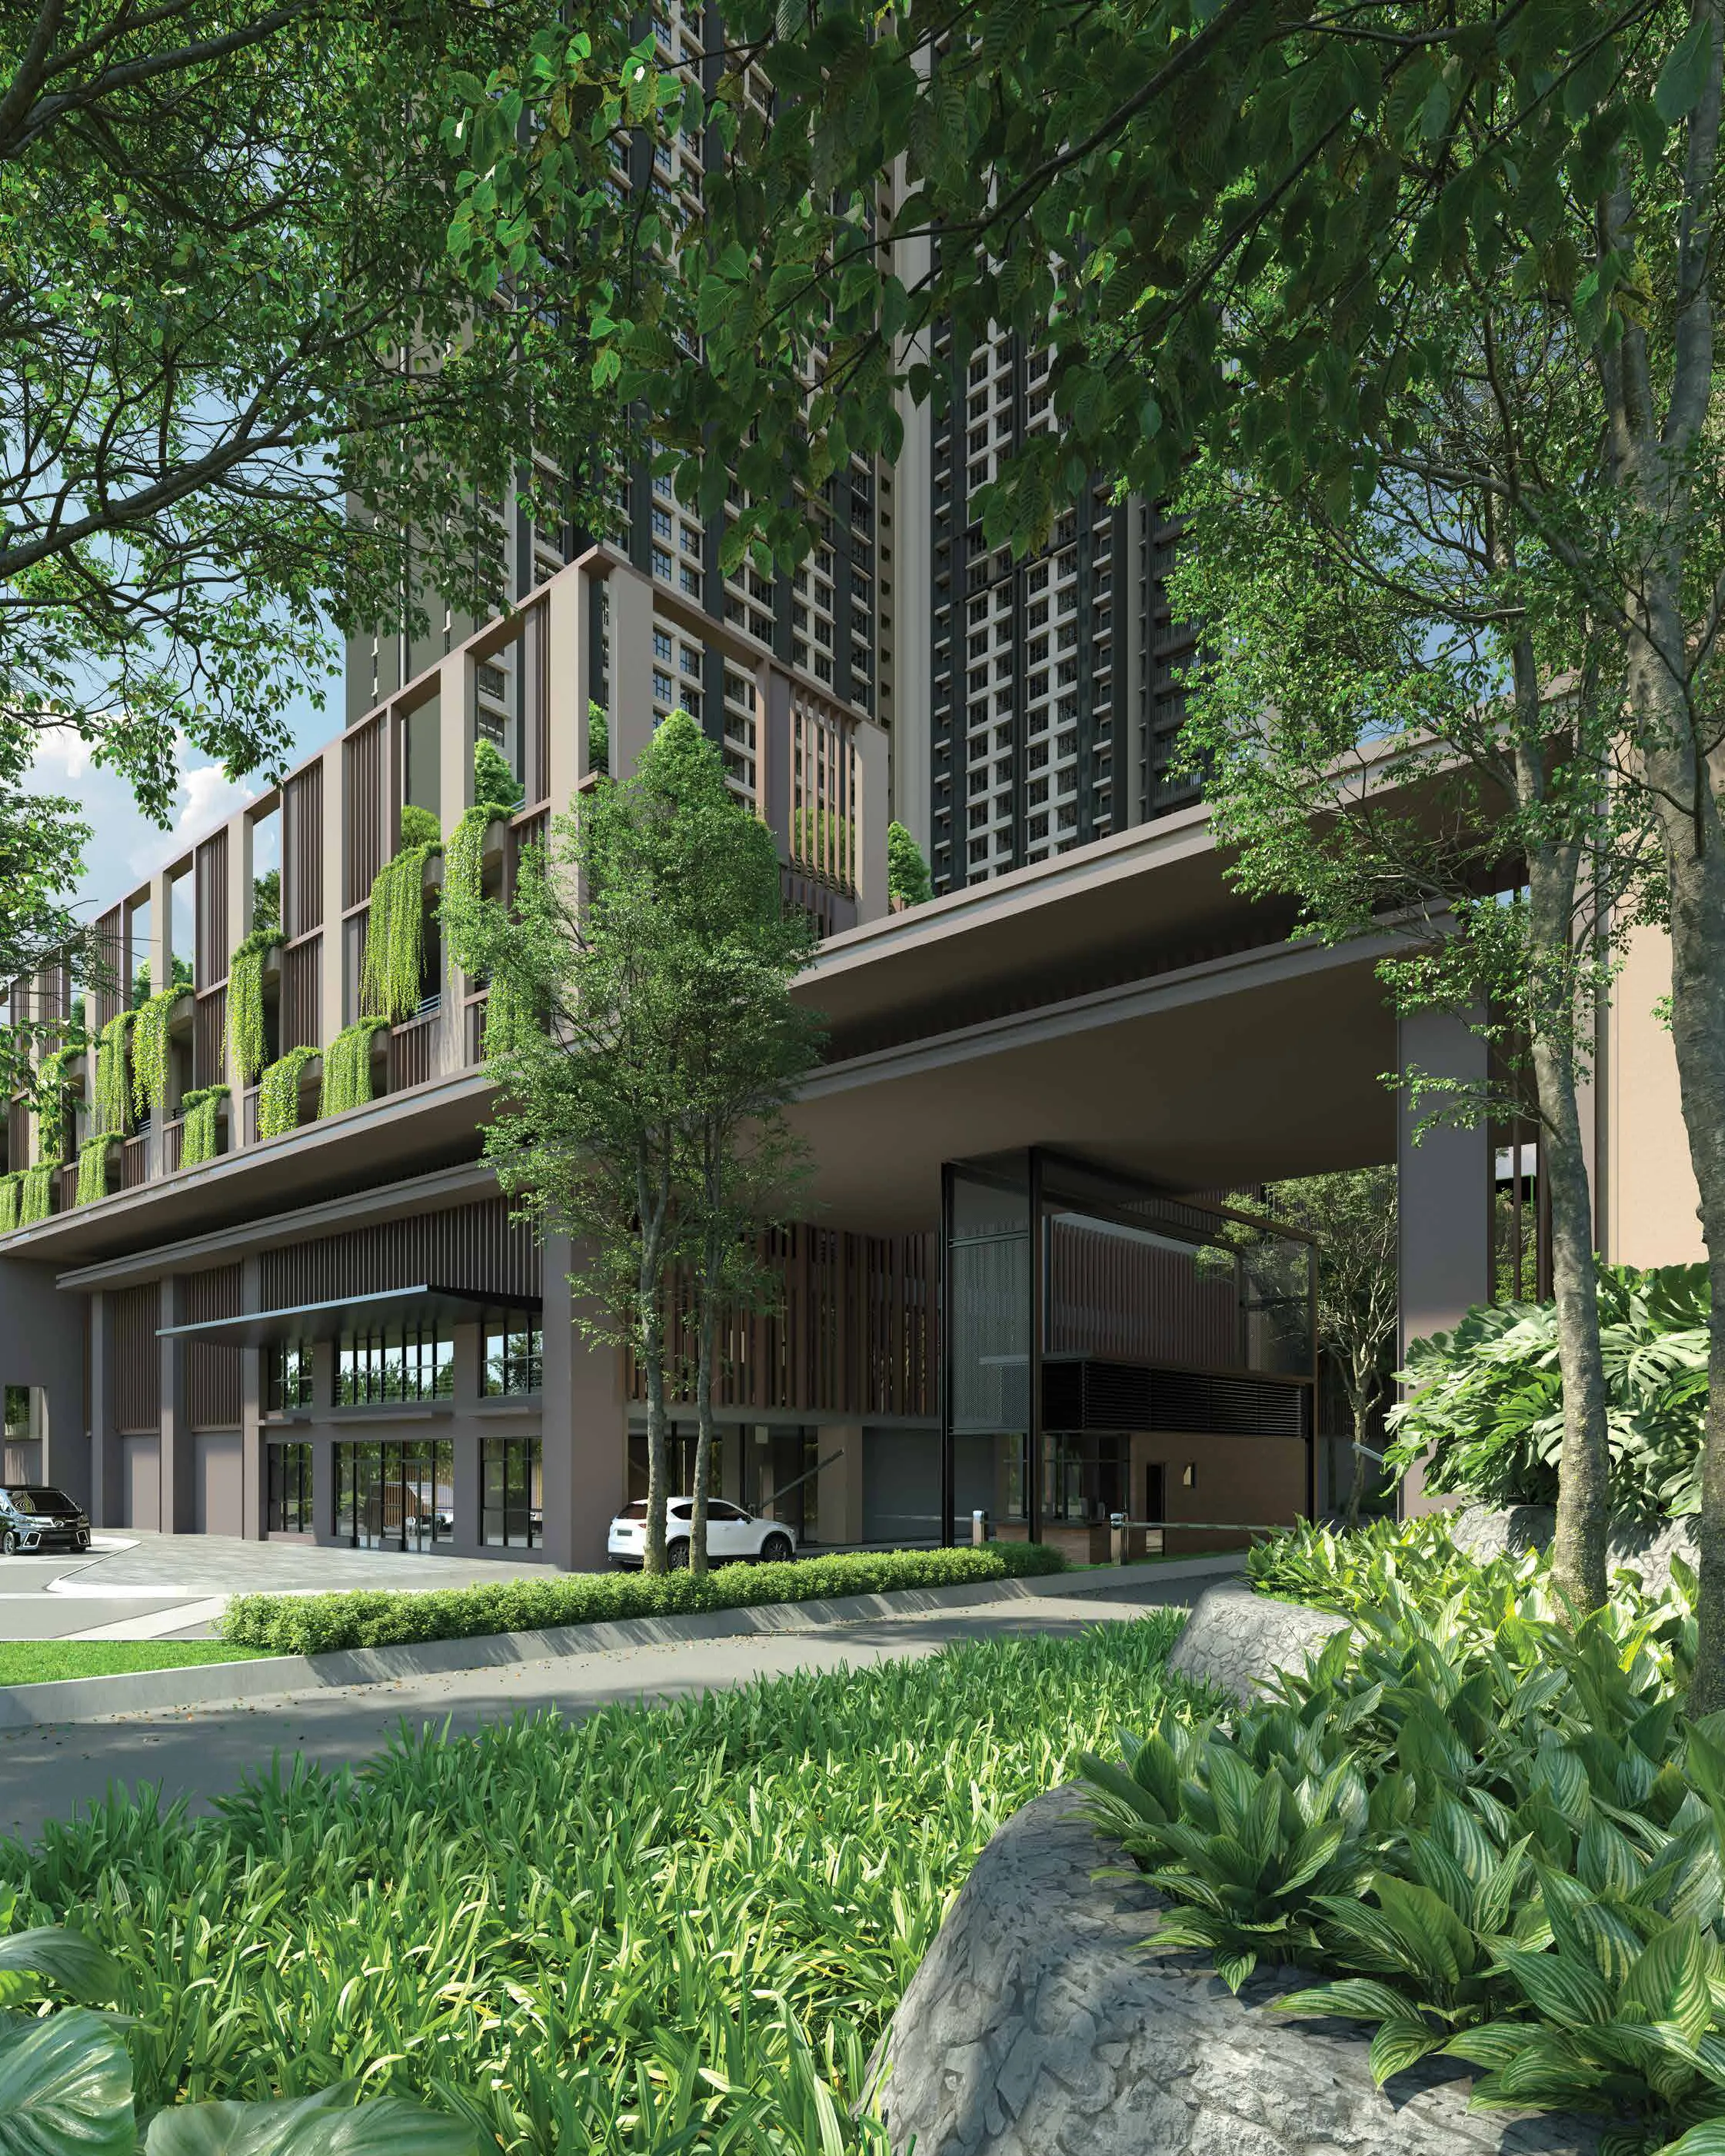
Artist’s impression · The Atera, in Petaling Jaya
How do you buy from overseas, step by step?
- Free loan check: send us your latest payslip and we tell you what the banks are likely to lend.
- Choose and book: we send the price lists and floor plans, and you book the unit you like.
- Matched to the right banks: we match your salary, job and country to the banks whose rules suit them, prepare your file with you, and submit it only to those. You then compare their offers and choose.
- Sign: the SPA and loan agreement, abroad where the developer and bank allow it, or on a trip back.
- Pay as it is built: your share of the stage bills first, then the bank pays the rest from your loan.
- Keys: move in when you are back, hand them to your family, or rent the home out.
Can you buy and sign from overseas?
- View by video: we walk you through the show unit or the finished home on a video call, or book a viewing for when you are back.
- Signing abroad: many developers and banks accept an SPA and loan agreement signed before a notary or at a Malaysian embassy or high commission, and some take a power of attorney. Some ask you to sign in person, so we check the developer and the bank for you before you book, and plan the signing around your next trip back if needed.
- Borrow in Singapore dollars: CIMB Singapore lists a Malaysia property loan in S$ for homes in Kuala Lumpur, for buyers earning over S$60,000 a year, on the bank’s own approval. A ringgit loan from a Malaysian bank is the other way.
- Pay from abroad: the down payment and stage bills are paid by transfer, and the bank pays its share directly to the developer.
Working overseas and ready to buy?
Tell us where you work and your budget. We send you the homes that fit, and the banks that lend on your salary.
- Which homes fit your salary?
- Which banks count the most of it?
- What is the cash to sign at your price?
Three new launches open to you, two of them closed to foreign buyers.

The Atera
A covered walk to the LRT, one train to KL Sentral
Own stay 4.3/5Investment 4.3/5
- From
- RM691,400
- Bedrooms
- 2–4 bedrooms
- Completion
- October 2028
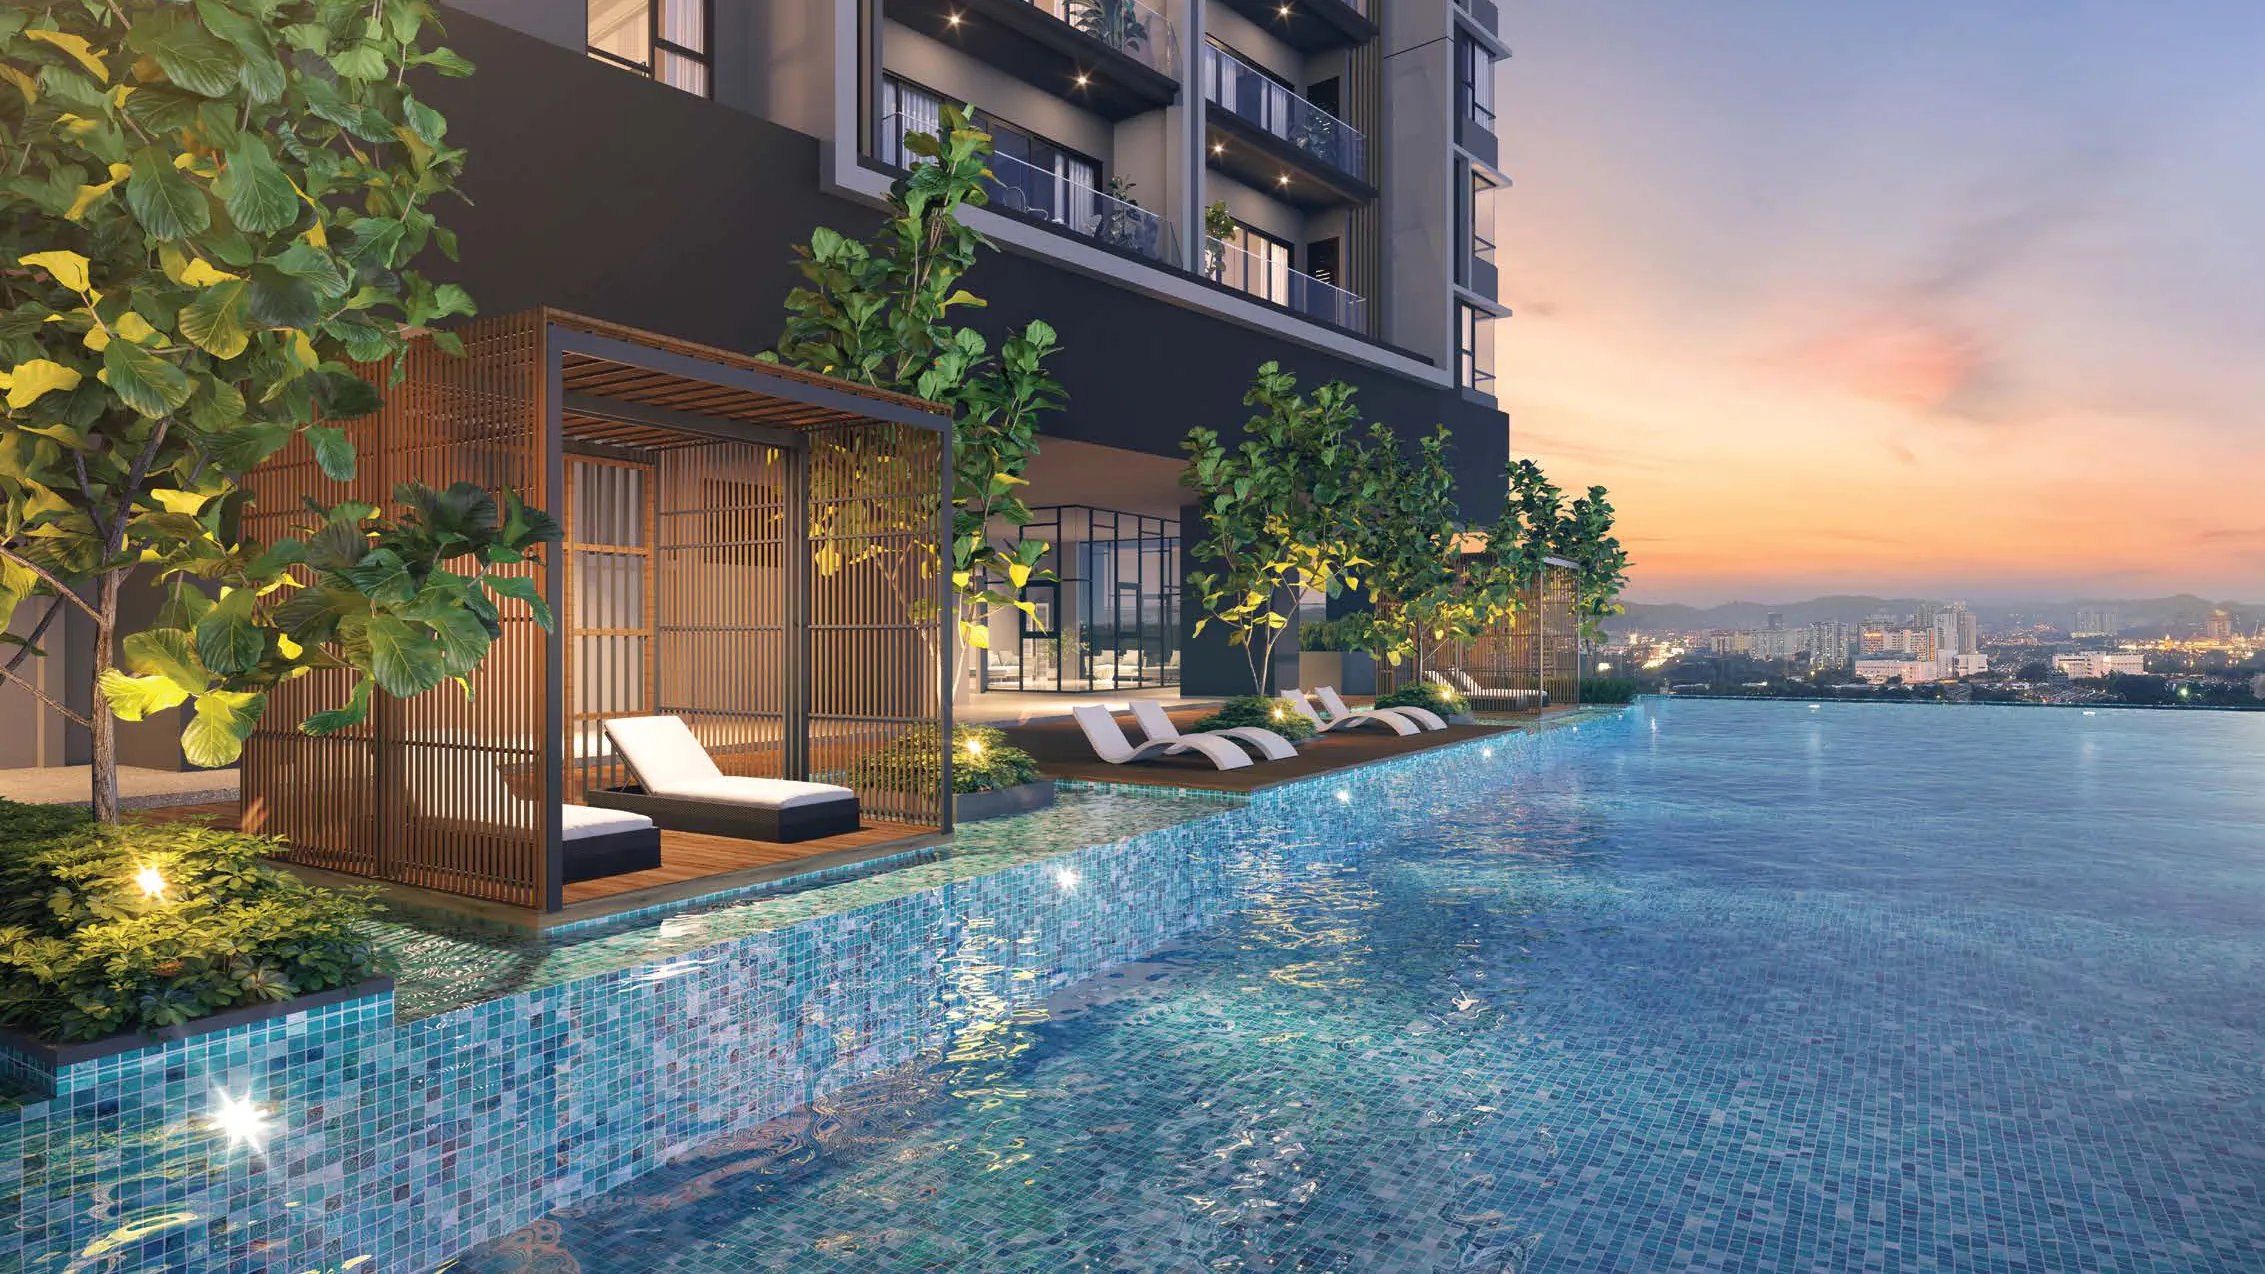
OAKA Residences
Freehold family homes beside the golf course
Own stay 4.3/5Investment 4.2/5
- From
- RM854,000
- Bedrooms
- 2–3 bedrooms
- Completion
- February 2028
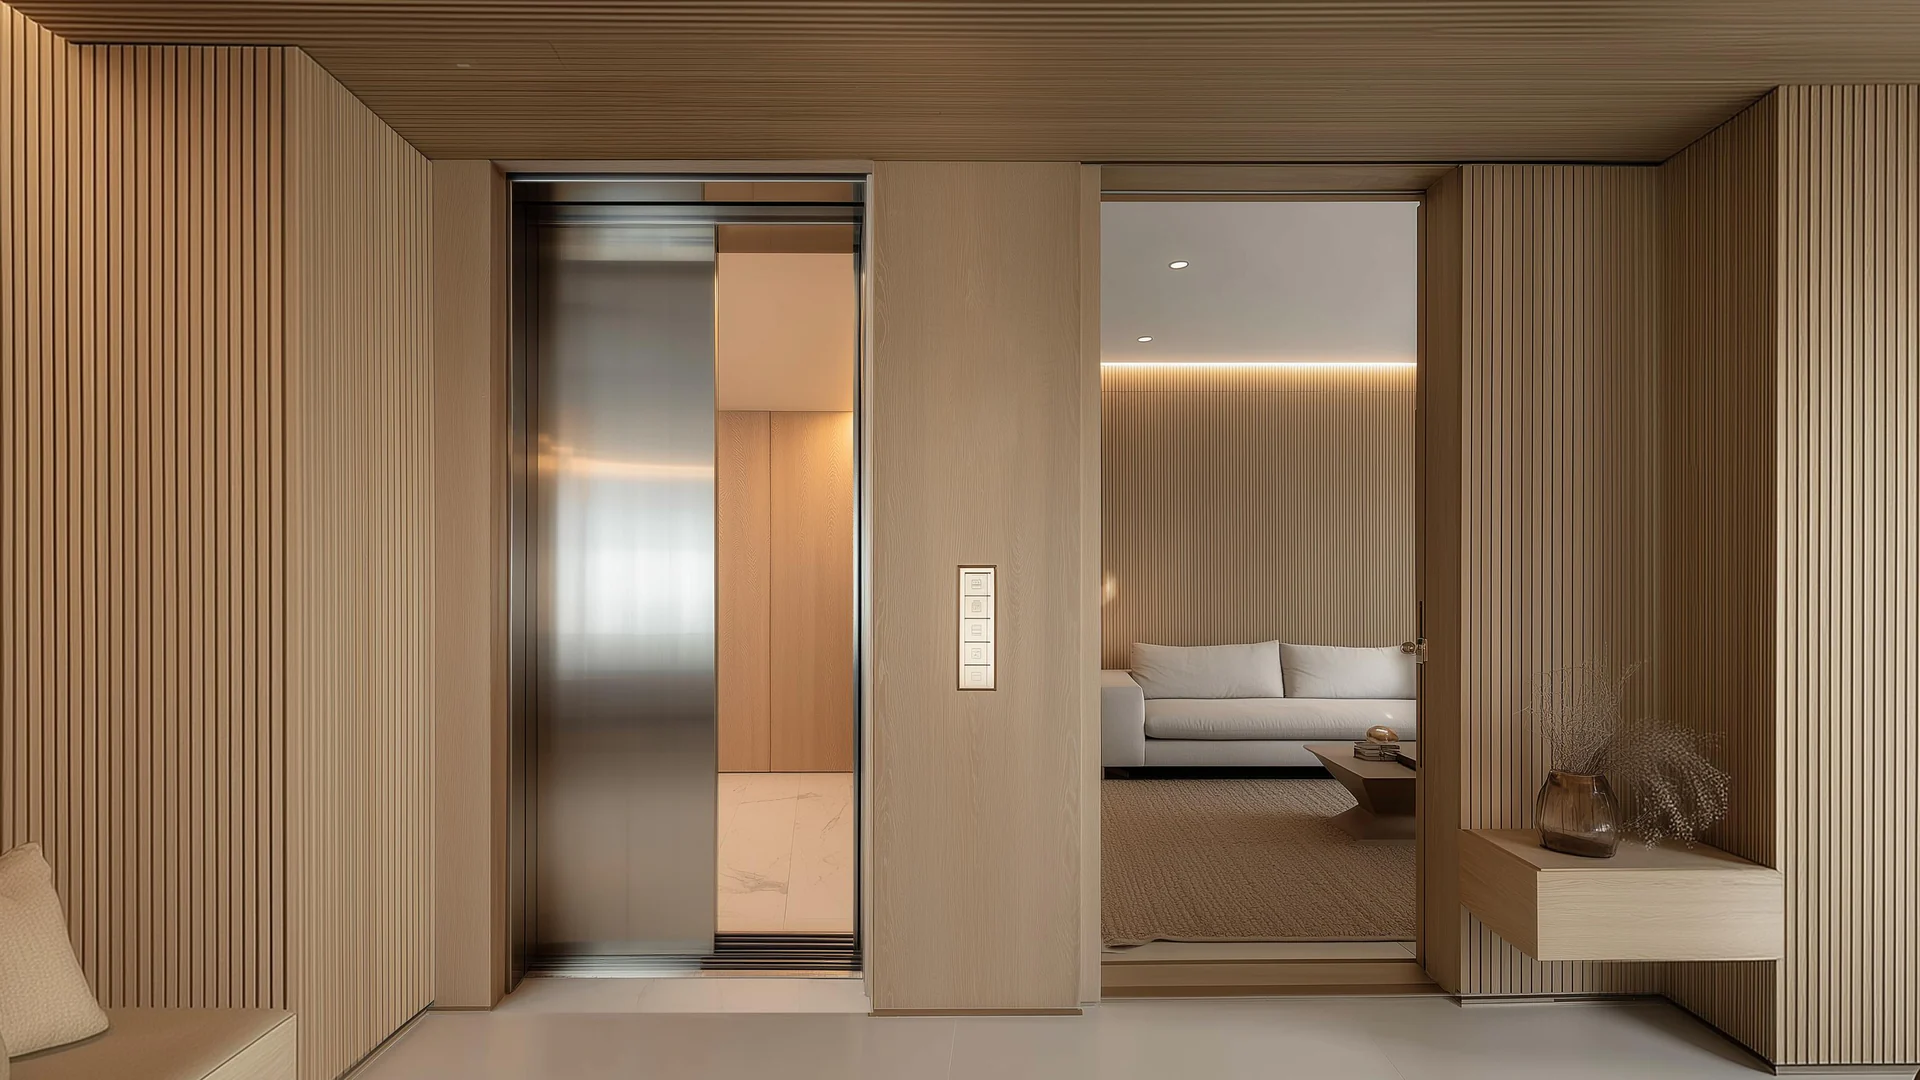
Accent Residences
Semi-D in the sky, private lift lobby
Own stay 4.5/5Investment 3.8/5
- From
- RM1.15mil
- Bedrooms
- 3–4 bedrooms
- Completion
- 2030